If your credit card balances are creeping up on you, it may be time for a refinance
Total US household debt continues to climb even as borrowing costs rise with higher interest rates, particularly on credit cards. The total debt level for. credit cards hit a record of $1.29 trillion…with a T!!! And it seems on pace to keep on climbing.
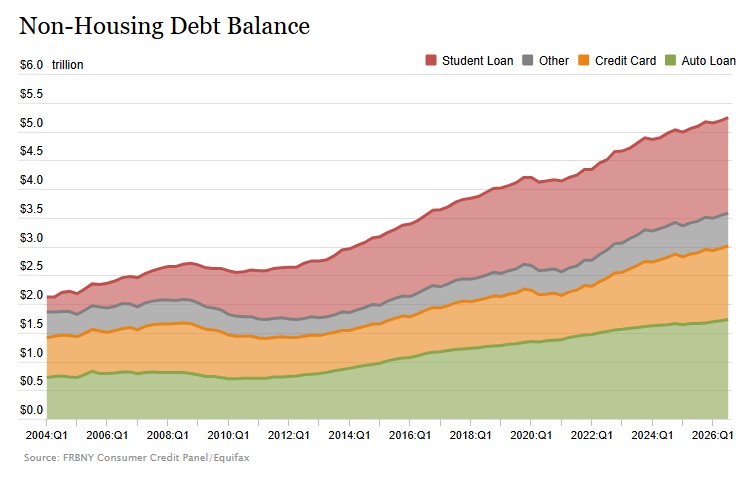
Many of us are facing harder times with the on-going economic slow down & lingering inflation. With credit card balances & their interest rates at all-time highs, it may be time to consider a cash-out refinance or 2nd mortgage to consolidate high-rate loans.

Home values remain reasonably resilient & most homeowners have record levels of home equity. Even with elevated mortgage rates, it may be better to roll higher rate credit card debt into a new mortgage balance.
Has the economic slowdown or higher living costs forced you to borrow more against credit cards, cars, and education? Borrowing from your equity at a lower rate to pay off higher rate debt will lower your overall monthly payments and lower your interest costs over the long-run. I can help you determine the “blended rate” of your various debts, the effective interest rate you’re paying across all of your loans (including your mortgage). If your blended rate is over 7%, then its time to consider a cash-out refinance.
According to Forbes, the national average credit card interest rate is nearing 25%! With The Fed suggesting they don’t plan to reduce the Federal Funds Rate any time soon, this will lead to high credit card rates for some time.
Let us help alleviate the financial stress of carrying high credit card balances at astronomically high interest rates by refinancing them into a lower rate mortgage. We work with several lenders that offer many types of home loan programs, from fixed rate refinances to home equity lines of credit. We have the experience and compassion to help navigate your borrowing options in the most prudent ways possible.

